
Festive e-commerce sales India 2026 are presenting a contradiction. E-commerce platforms are reporting strong shopping activity, yet one market estimate points to lower gross merchandise value (GMV) than the comparable period last year. The difference raises a bigger question: are consumers shopping more without generating the same sales value?
According to Moneycontrol, Datum Intelligence estimated that online festive sales generated ₹29,800–30,900 crore between October 7 and 10, 2026, compared with ₹33,200 crore in the comparable period a year earlier—a decline of roughly 7–10%. Meanwhile, Amazon reported more than 100% year-on-year growth in products ordered during the opening phase of its Great Indian Festival. These figures measure different things, but together they raise a more useful question: is India shopping more without generating the same value of sales?
Festive E-Commerce Sales India 2026: What the Numbers Reveal
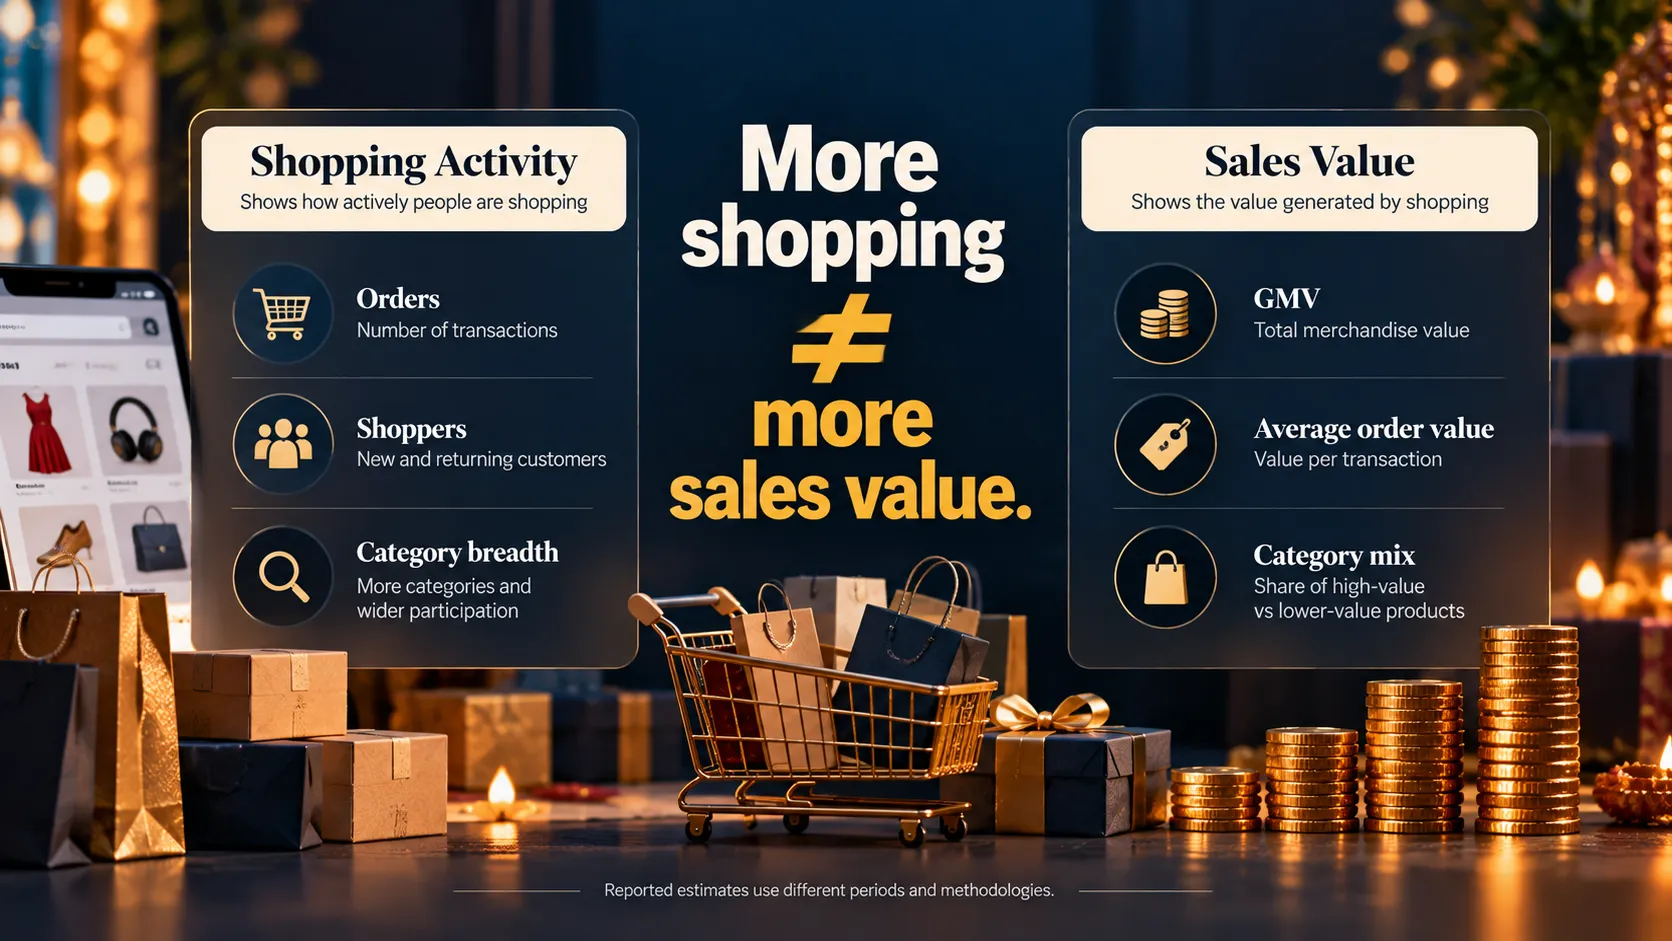
An increase in orders does not automatically mean an increase in GMV, or gross merchandise value. The number of transactions can rise while the average value of each transaction falls. Equally, a smaller number of expensive purchases can lift GMV without producing a comparable increase in order volume.
That distinction matters this year because the early festive market is being shaped by different price and category dynamics. Datum Intelligence, as reported by Moneycontrol, pointed to higher memory-chip and component costs pushing up smartphone and laptop prices, potentially weighing on big-ticket purchases. Last year’s festive opening also coincided with GST cuts, creating a different comparison base.
The result is a more complicated demand picture than a headline about record orders—or falling sales—can capture alone.
The shopping basket is changing
The early numbers also suggest that festive demand is not confined to premium electronics.
Redseer estimated that e-commerce platforms recorded around ₹24,000 crore in GMV over October 8 and 9, with approximately 8–9 crore orders. It also estimated that fashion GMV grew 22–25% year-on-year during those first two days, accounting for 15–18% of sales. These are estimates for a different time window from Datum Intelligence’s four-day figures, so they should not be directly combined.
The broader signal is that festive shopping can remain active while the contribution of individual categories shifts. Fashion, beauty, home products and everyday essentials can help sustain transactions even when higher-priced electronics face affordability pressure.
The broader signal is that festive demand is not confined to electronics. As shoppers explore more categories and purchase occasions, quick commerce’s role in brand discovery and purchase also becomes relevant, particularly as digital shelves influence which products consumers notice and choose.
For marketers, this changes the question from “How much did the sale grow?” to “Which categories are contributing to that growth, and at what price points?”
Affordability is becoming part of the offer
Discounts are only one part of the affordability equation. Exchange offers, bank incentives and EMI options can influence whether a shopper buys now, chooses a more expensive product or postpones the purchase.
Amazon’s own opening-sale update reported that more than one in three customers chose EMI during the early phase. This is platform-reported data, not a market-wide measure, but it highlights how payment mechanisms have become part of the purchase proposition.
That has implications for brand strategy. A product’s effective affordability may depend not just on its listed price, but on the monthly payment, exchange value and available incentive. Yet financing can also make a purchase easier without proving that consumers have greater room in their budgets.
Brands therefore need to distinguish genuine demand from demand that depends heavily on incentives. The two can look similar in a sales dashboard but produce different outcomes once discounts, returns and contribution margins are considered.
What brands should watch next
The opening days are a signal, not a verdict on the full festive season. The next phase should be assessed through four measures:
- GMV and order growth together: Is merchandise value recovering alongside transaction volume?
- Average order value: Are consumers buying smaller baskets, lower-priced alternatives or more items per order?
- Category contribution: Are fashion, beauty and home products offsetting pressure in electronics, or simply adding volume?
- Commercial quality: Are sales translating into healthy margins and repeat behaviour, or relying on costly promotions and financing?
These measures help separate a high-activity sale from a commercially strong one. They also show why brands should examine how commerce is becoming a testing ground for brands, using consumer response across categories and purchase occasions to identify which propositions deserve further investment.
These measures help separate a high-activity sale from a commercially strong one.
Conclusion
Festive e-commerce is increasingly difficult to understand through a single growth number. A platform can report record orders while the wider market’s GMV moves in the opposite direction. A category can grow quickly without compensating for weakness in a higher-value category. And a promotion can unlock purchases without necessarily creating durable preference.
For brands, the strategic task is to read the composition of demand—not just its headline. The strongest festive performance will not necessarily belong to the brand generating the most transactions, but to the one that understands which shoppers are buying, what they are choosing, what makes the purchase affordable and whether the economics remain attractive after the sale.
The season is still unfolding. The more revealing result will be whether today’s shopping activity turns into sustained value.